 By
Growing a business often requires more capital than day-to-day cash flow can comfortably provide. Whether a company wants to hire staff, invest in equipment, open a new location, increase stock, or expand into new markets, the right type of finance can help fund growth without putting unnecessary pressure on working capital.
UK businesses have access to a wide range of funding options, from traditional bank lending to specialist forms of commercial finance. The best choice depends on the size of the business, its financial position, how quickly funding is needed, and what the money will be used for.
Businesses exploring their options can use WiT Money’s business finance comparison to review different types of funding available in the UK.
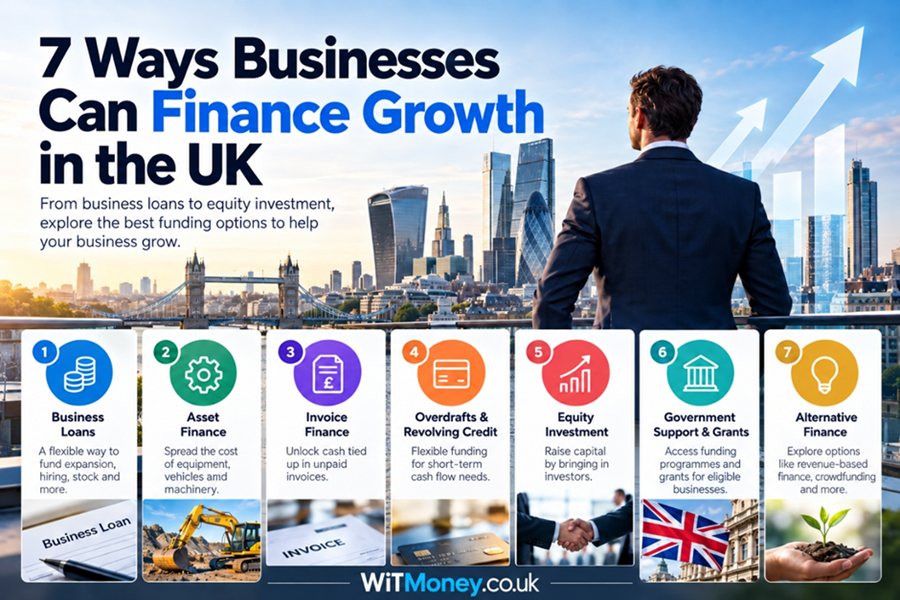
1. Business Loans
Business loans are one of the most familiar ways to finance growth. A lender provides the business with a lump sum, which is then repaid over an agreed period with interest.
Funding can be used for a wide range of purposes, including:
- hiring additional employees
- marketing campaigns
- purchasing stock
- refurbishing premises
- launching new products
- expanding into new locations
- improving technology or systems
Business loans may be secured or unsecured. Secured loans usually require an asset as security, while unsecured loans do not normally require a specific asset to be pledged, although personal guarantees may sometimes be requested.
Repayment terms can range from months to several years depending on the lender and amount borrowed.
Companies considering this type of finance can compare UK business loans with WiT Money to explore different borrowing options.
Business loans can be particularly useful where a company knows how much capital it needs and wants a predictable repayment schedule.
2. Asset Finance
Businesses that need expensive equipment, vehicles or machinery may prefer asset finance rather than paying the full cost upfront.
Asset finance can help fund purchases such as:
- manufacturing machinery
- commercial vehicles
- construction equipment
- agricultural machinery
- IT hardware
- specialist medical equipment
- office equipment
Two common forms are hire purchase and leasing.
With hire purchase, the business typically makes regular payments over an agreed term and may own the asset once the final payment has been made.
With leasing, the company generally pays to use the equipment for a set period without necessarily purchasing it outright.
Asset finance can preserve cash for other areas of the business while allowing the company to access equipment needed for expansion.
3. Invoice Finance
Rapid growth can sometimes create cash-flow problems rather than solve them.
A company may generate significant sales but still have to wait 30, 60 or even 90 days for customers to settle invoices. Meanwhile, wages, suppliers, rent and other expenses still need to be paid.
Invoice finance allows businesses to access part of the value of unpaid invoices before customers pay them.
There are two main approaches.
Invoice factoring typically involves a finance provider advancing funds against outstanding invoices and often managing collections.
Invoice discounting also releases cash against unpaid invoices, but the business may retain responsibility for collecting payments.
This type of funding can be particularly useful for companies growing quickly or operating in industries where long payment terms are common.
4. Business Overdrafts and Revolving Credit
Not every growth opportunity requires a large one-off loan.
Some businesses need flexible access to additional working capital rather than a fixed amount borrowed upfront.
A business overdraft allows a company to spend beyond the available balance in its current account up to an agreed limit.
Revolving credit facilities operate in a similar way, allowing businesses to draw funds when needed, repay them and potentially borrow again within the agreed facility.
This can be useful for:
- short-term cash-flow gaps
- seasonal businesses
- temporary increases in stock requirements
- unexpected expenses
- supplier payments
The main advantage is flexibility. Businesses normally pay interest on the amount actually used rather than the entire available facility.
However, rates and fees can vary considerably, so the total cost should be considered carefully.
5. Equity Investment
Borrowing is not the only way to finance growth.
Some businesses raise capital by selling part of the company to investors. These may include:
- angel investors
- venture capital firms
- private equity investors
- strategic corporate investors
- family offices
Equity investment does not usually require monthly repayments in the same way as debt financing.
Instead, investors receive ownership in the business and may benefit if the company grows in value.
Equity can be particularly suitable for high-growth companies where future potential is significant but current cash flow may not support large loan repayments.
The trade-off is that existing owners give up part of their ownership and potentially some control over business decisions.
For founders, the choice between debt and equity often depends on whether preserving ownership or avoiding regular repayments is the bigger priority.
6. Government-Backed Finance and Grants
Some UK businesses may qualify for government-backed funding programmes or grants.
Support can vary depending on factors such as:
- business location
- industry
- company size
- innovation activity
- research and development
- environmental projects
- export activity
Grants can be especially attractive because they may not need to be repaid.
However, they are often highly competitive and may come with strict eligibility requirements.
Government-backed lending programmes may also help businesses access finance where traditional lending would otherwise be difficult.
Companies should check current eligibility criteria carefully because schemes can change over time.
7. Revenue-Based and Alternative Finance
The UK business finance market has expanded significantly beyond traditional bank loans.
Alternative funding options can include:
- revenue-based finance
- merchant cash advances
- peer-to-peer business lending
- crowdfunding
- trade finance
- purchase-order finance
Revenue-based finance typically allows a company to repay funding as a percentage of future revenue.
This can make repayments more flexible because they rise and fall with sales.
Merchant cash advances work in a similar way for businesses that process significant volumes of card payments. Repayment may be linked directly to future card transactions.
These forms of finance can be useful for businesses that need fast access to capital or have revenue patterns that do not suit traditional fixed monthly repayments.
However, businesses should compare the total repayment amount carefully because alternative finance can sometimes be more expensive than conventional lending.
How to Choose the Right Finance for Business Growth
The most suitable funding option depends on the purpose of the finance and the financial position of the company.
A business buying machinery may find asset finance more appropriate than a general loan.
A company with large unpaid invoices may benefit more from invoice finance.
A technology startup pursuing rapid expansion may prefer equity investment.
A profitable SME with predictable cash flow may find a traditional business loan easier to manage.
Before choosing a funding option, businesses should consider:
- how much funding is needed
- how quickly the money is required
- the total cost of borrowing
- repayment terms
- whether security is required
- whether personal guarantees are involved
- how repayments affect cash flow
- whether ownership dilution is acceptable
Comparing several forms of funding can help business owners understand which structure best matches their growth plans.
Comments